Fed Rate Hikes Will Increase US Interest Costs By $50 Billion
The short version
- That's because markets tend to respond to changes in the expected path of deficits and Treasury issuance rather than the level of debt alone.
- Importantly, there has been no policy announcement or fiscal development that meaningfully altered those expectations recently.
- Regardless of what has driven the rise in yields, the BofA economist team cautions that higher interest rates across the curve do warrant a renewed focus on deficits.
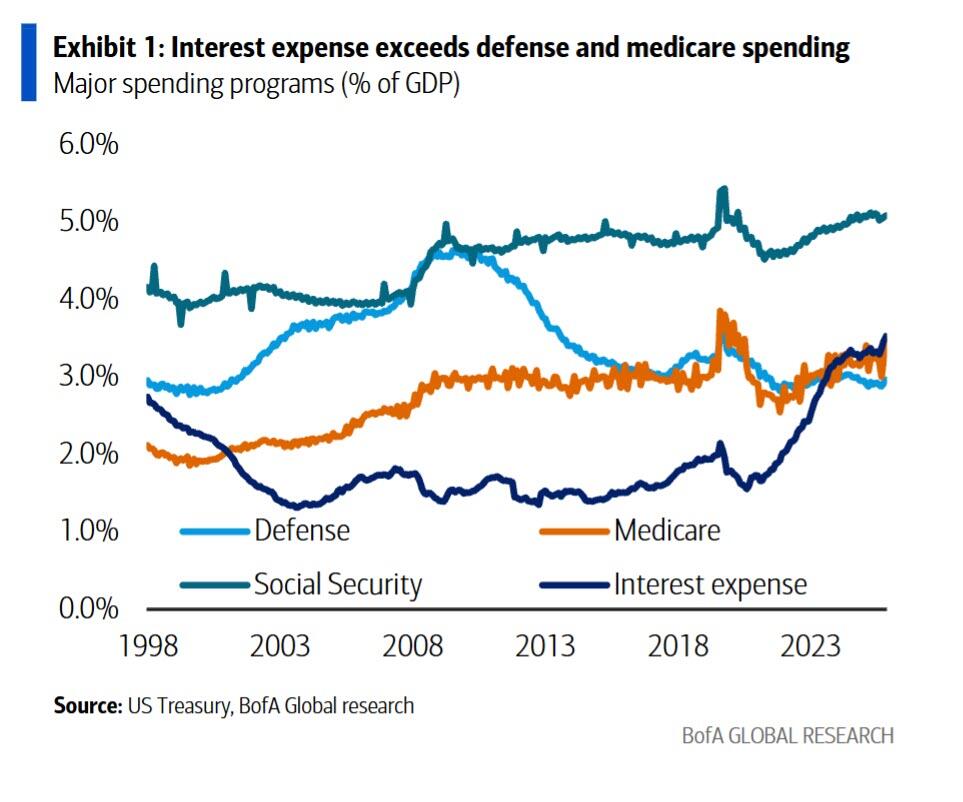
- The deficit this year is on pace to once again eclipse 6% of GDP and a major reason for that is rising interest expense which has exceed spending on Defense and Medicare.
- The trend in interest costs is also notably worse than Medicare, Defense Spending and even Social Security, which have been more stable.
The story
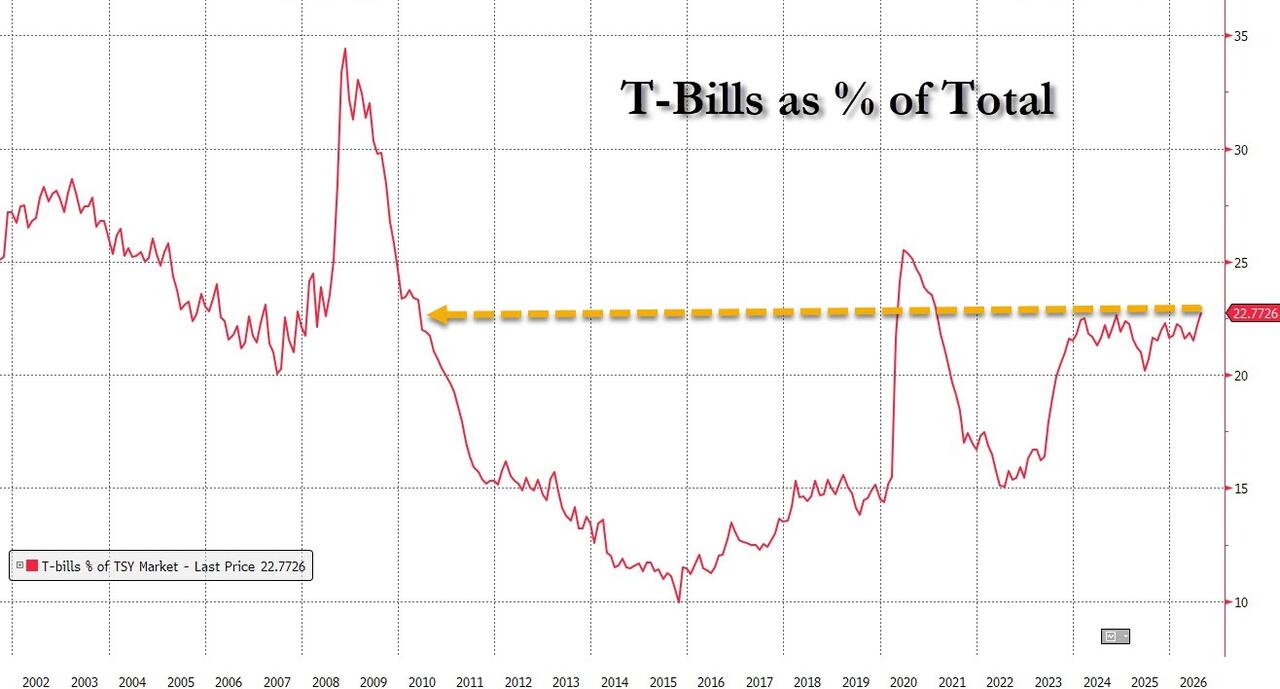
The biggest problem with the "short-terming" of the US Treasury stock, which under Bessent's extension of Yellen's Activist Treasury Issuance playbook, which pushed the percentage of T-Bills as a percentage of total debt to 23% - the highest since 2010 excluding the emergency surge during the covid crisis which relied entirely on Bills for government funding and briefly pushed the Bill percentage above 25% - even as total US debt rose above $40 trillion for the first time ever...
... is that any rate hike will immediately increase the amount the country is spending on interest.
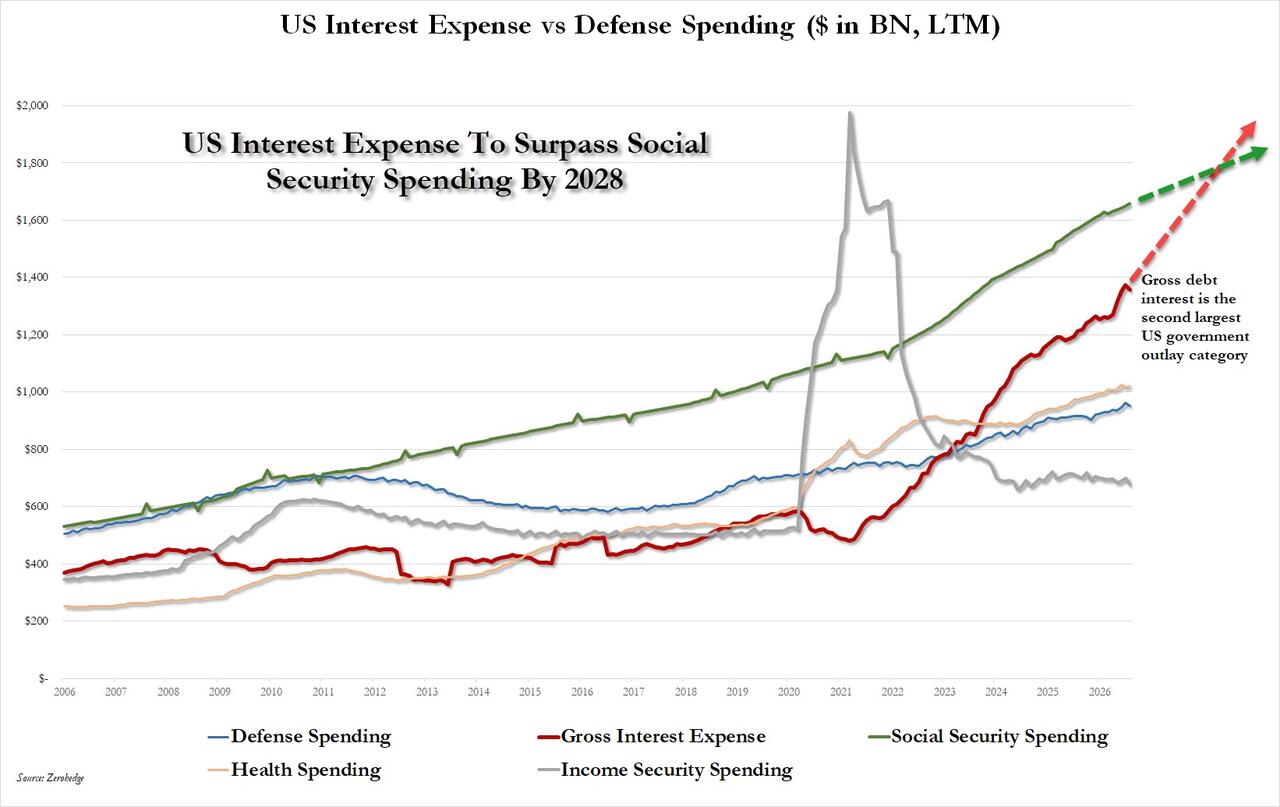
Which is especially concerning because, as we wrote on Friday when discussing the August budget deficit, gross US interest (for the LTM period) is now a record $1.4 trillion and is set to surpass Social Security as the largest US outlay within 2 years, likely hitting $2 trillion before 2030.
The dramatic deterioration in the US fiscal picture prompted BofA's chief economist Aditya Bhave to pen a report ("In the interest of time", available to pro subs) in which he wrote that "the recent rise in interest rates, particularly at the long-end, coupled with US total debt crossing the $40tn threshold sparked a wave of commentary on the US fiscal picture."
According to Bhave, while elevated deficits since the pandemic have certainly contributed to the higher term premium, it’s unlikely that crossing the $40tn threshold contributed to the recent increase in long-term yields. That's because markets tend to respond to changes in the expected path of deficits and Treasury issuance rather than the level of debt alone. Importantly, there has been no policy announcement or fiscal development that meaningfully altered those expectations recently.
Instead, BofA notes, it appears that the recent rise in yields has been driven by higher inflation expectations owing to the rise in energy prices and questions over the Fed’s commitment to its price stability mandate, which were partially quieted by Warsh at Jackson Hole.
Regardless of what has driven the rise in yields, the BofA economist team cautions that higher interest rates across the curve do warrant a renewed focus on deficits. The deficit this year is on pace to once again eclipse 6% of GDP and a major reason for that is rising interest expense which has exceed spending on Defense and Medicare. The trend in interest costs is also notably worse than Medicare, Defense Spending and even Social Security, which have been more stable.
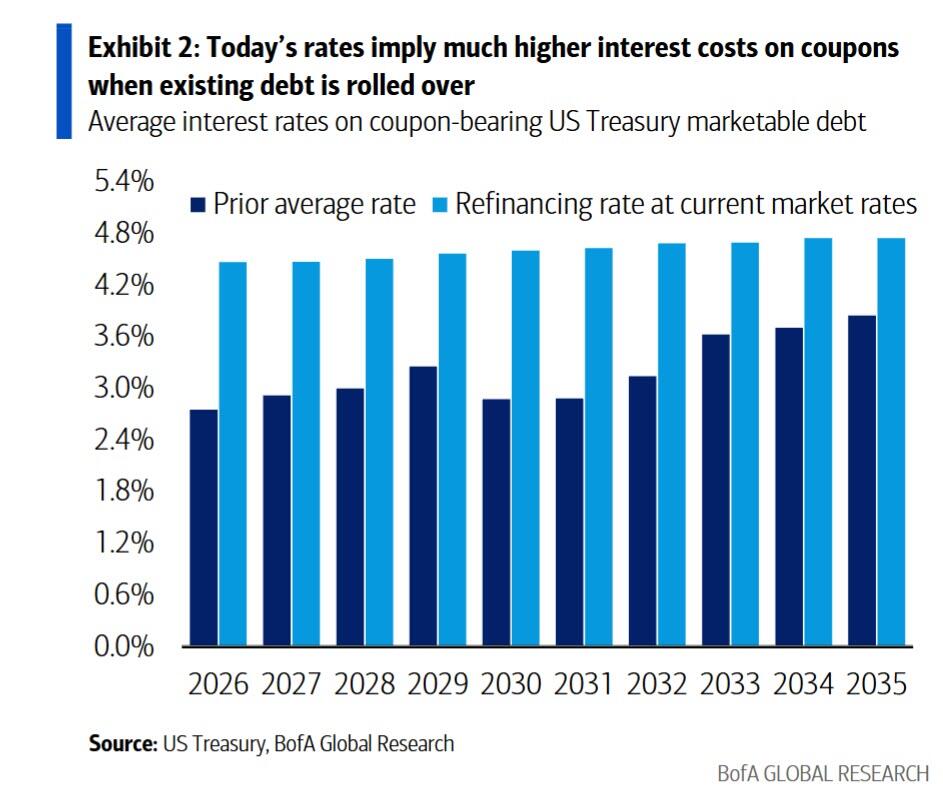
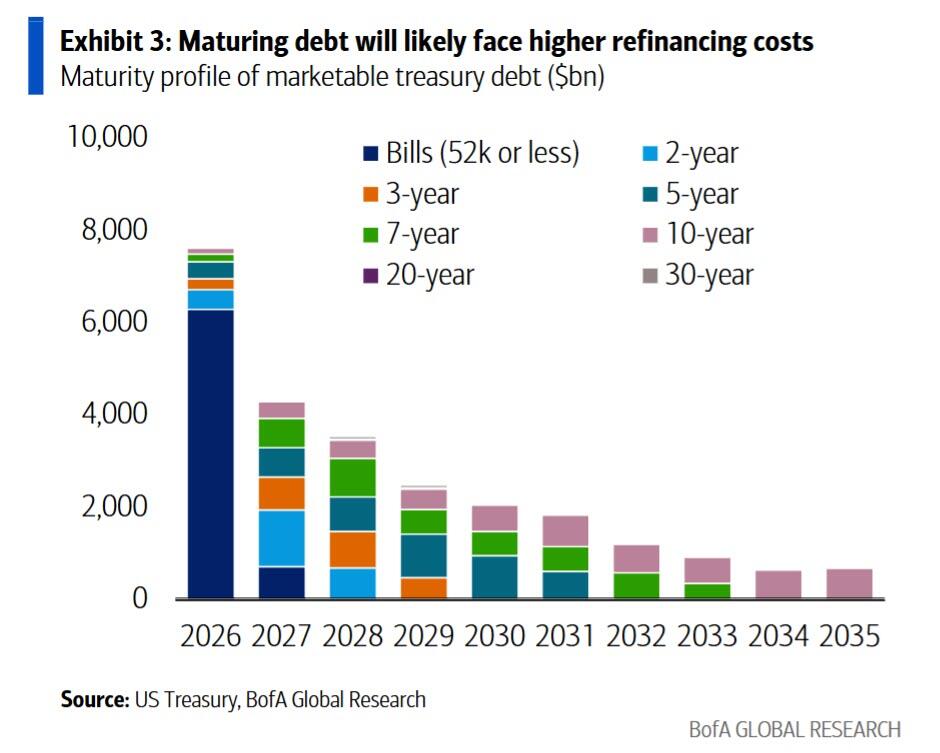
And while the trend of US interest expense growth is already ruinous, here BofA repeats what we said above, namely that the current level of interest rates is likely to exacerbate these trends as Treasury refinances maturing debt at higher borrowing costs.
According to BofA calcs, the average interest rate on outstanding marketable Treasury debt remains well below prevailing market yields, at roughly 3.4%. Looking specifically at coupon-bearing securities, current market rates imply that debt rolled over in coming years will be refinanced at interest rates approximately 1.4 percentage points higher, on average, than those on the securities being retired.
Most importantly, and this is what we started the post with, is that the Treasury's increased reliance on bills also leaves borrowing costs more sensitive to near-term monetary policy. As Bhave writes, nearly $7 trillion of Treasury bills are currently outstanding, the vast majority of which mature within one year.
Assuming the Fed hikes rates by 75bp this year as BofA expects (once this week, and two more times before the latest Fed Hiking cycle ends), BofA concludes that annual interest costs on outstanding T-bills could increase by roughly $50bn or ~15bps of GDP.
It gets worse.
As a reminder of the pernicious nature of compounding debt, in addition to higher refinancing costs on the horizon, BofA warns that a more fundamental concern is the feedback loop between interest rates and debt. Ultimately, debt sustainability depends not only on the level of interest rates, but also on how those rates compare with nominal GDP growth. When nominal growth exceed borrowing costs, debt-to-GDP ratios can stabilize over time. However, as the gap between interest rates and nominal growth narrows, higher debt levels become increasingly difficult to sustain.
The risk is that the self-reinforcing dynamic between interest costs and deficits can further narrow that gap over time.
Meanwhile, there is a feedback loop between higher interest costs and deficits that we must account for. Higher interest costs increase deficits and Treasury borrowing needs, which in turn result in even more interest expense. Increased Treasury issuance can put upward pressure on term premiums as investors demand greater compensation to absorb a larger supply of duration. Higher term premiums raise borrowing costs, which further increase interest expense and deficits, creating a self-reinforcing dynamic.
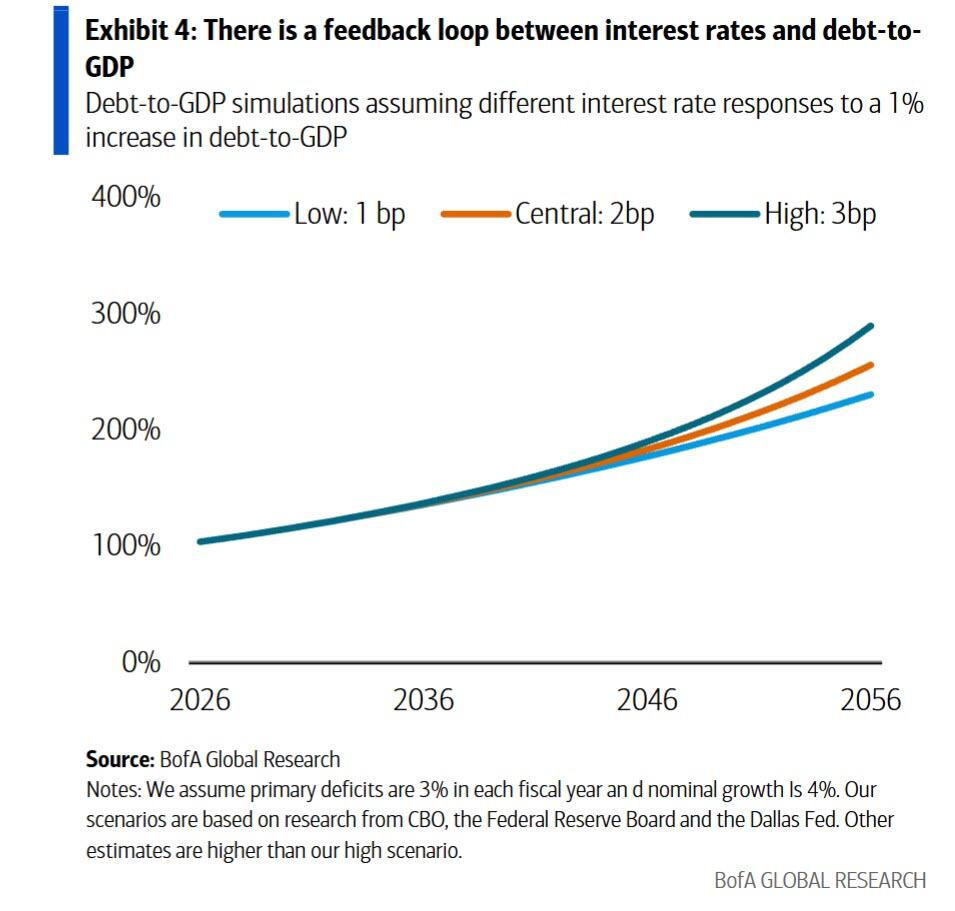
Obviously, the risk from this dynamic is not immediate, which only makes it worse as generations of politicians can sweep it under the rug (dealing with unsustainable spending and debt is not only unpleasant, it is a career killer for politicians), until it becomes to late to deal with it and the problem explodes. Sure enough, this dynamic emerges only gradually as a larger share of the debt stock is refinanced at higher rates and interest expense consumes an increasing share of federal spending. To illustrate this, BofA simulates debt-to-GDP trajectories under three scenarios for how interest rates respond to higher debt.
In the low, central, and high scenarios, a 1 percentage point increase in the debt-to- GDP ratio raises interest rates by 1bp, 2bp, and 3bp, respectively. While the effects are modest initially, the trajectories diverge meaningfully over longer horizons as higher debt levels lead to higher borrowing costs, which further accelerate debt accumulation.
The composition of deficits matters
The growing share of deficits attributable to interest costs has important implications for both the economy and financial markets. That's because deficits driven by rising interest expense provide far less support to economic activity than deficits associated with tax relief or government spending, and are far less defensively politically. In addition, they may crowd out both public and private investment by placing sustained upward pressure on long-term interest rates. Over time, they constrain the government's ability to provide fiscal support during economic downturns, potentially slowing the pace of recovery and resulting in a full-blown fiscal crisis.
For markets, the changing composition of deficits matters because it can lead to greater Treasury issuance without a corresponding boost to economic growth. As a result, it may place additional upward pressure on Treasury supply, term premiums, and ultimately the long end of the yield curve.
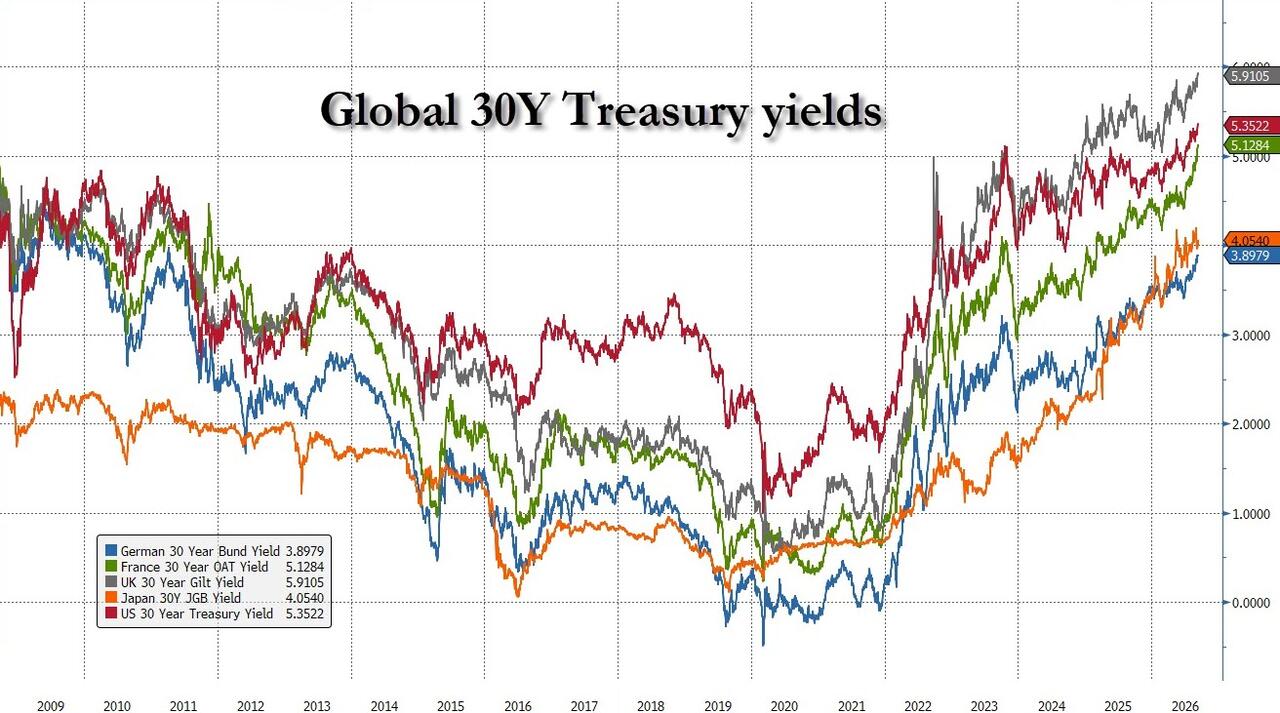
To see this in practice, look no further than interest rates on the long-end of the Treasury curve... but not just in the US - anywhere else too.
In conclusion, nobody wins from adding another $50 billion of interest cost to the country (except for America's short-term creditors of course). As Peter Tchir wrote earlier, with interest expense already an issue relative to defense or discretionary spending, a rate hike does not help on that front.
Putting it together, the Academy Securities trader wrote that he finds it "difficult to imagine President Trump liking the idea, even if it helps the longer end of the yield curve, or that stocks have priced it in."
Of course they haven't, but stocks remain hypnotized in an AI-bubble, which ironically is kept afloat only thanks to record debt issuance (now that capex is funded largely from new debt), which will come to a crashing halt once Treasury yields spike and the credit market slams shut once. And as always happens, all of these things will take place all at once triggering the next Fed bailout of, well, everything.
More in the full BofA note available to pro subscribers
Related Markets
All MarketsMarket data may be delayed. Not financial advice.
How this story developed
Full timelineAlto has tracked this across 56 days of coverage from 1 outlet.
- Fed Rate Hikes Will Increase US Interest Costs By $50 BillionYou are here
- Futures Slide As Tech Tumbles On Fears Of AI Slowdown, Oil JumpsZeroHedge
Powered by Gab AI
The Story At A Glance
Reading this article now — analysis appears below
💡 AI analysis provides alternative perspectives on current events